US Treasury Proposes Stablecoin Licensing Rule, Raises Questions on Compliance and Verification
September 6, 2026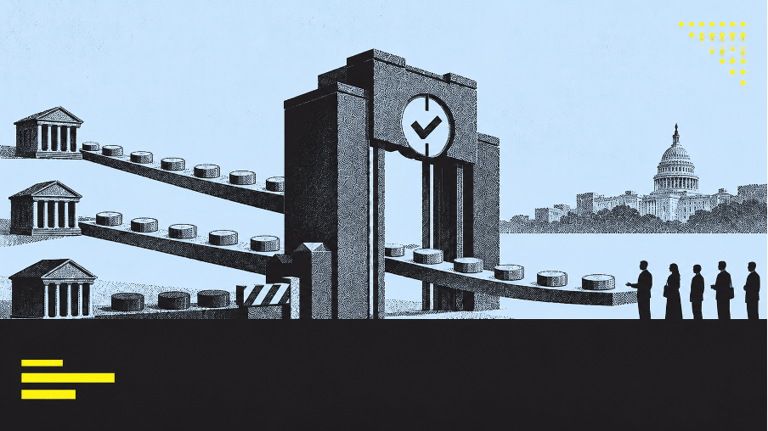

The U.S. Treasury released a proposed rule under the GENIUS Act aimed at creating a stablecoin regime with issuer licensing and distributor obligations for platforms selling to U.S. persons.
A core challenge is applying controls to high-velocity automated micropayments, which operate without human intervention and demand machine-speed identity, AML, and sanctions checks.
Issuers and custodians must choose between state charters or federal supervision and should prepare for enhanced transparency and reporting for individual accounts and wallets, including KYC and sanctions screening.
Open questions remain on operational compliance, such as how platforms verify permitted-issuer status, what documentation suffices, the 18-month gap between licensing and distributor obligations, and how large existing stablecoins like USDT would be treated if issuers aren’t deemed permitted.
Stablecoins are envisioned as enabling an internet-native payment system, with examples like a payments protocol enabling AI agents and collaborations with major cloud providers to support such payments.
Regulated institutions must adjust compliance controls for stablecoins, while crypto-native issuers will face heavier requirements drawing on traditional banking disclosures, operations, and supervisory practices.
The GENIUS Act provides legal legitimacy for stablecoins, but practical compliance systems will determine scalability without compromising existing financial safeguards.
The architecture foreseen combines regulated digital money, blockchain records, decentralized entities, and autonomous software to create a faster, cheaper payments layer largely operating behind the user’s click.
Penalties under the GENIUS Act can reach up to $1 million per violation, with imprisonment up to five years for knowing participation in unlawful issuance.
The NPRM sits within a broader regulatory stack, with ongoing rulemaking by OCC and Federal Reserve and key dates for public comments and phased effective dates in late 2026 through 2028.
Federal agencies like the OCC, FDIC, and NCUA are developing a framework covering custody, BSA/AML, sanctions, capital, and risk management for issuers and custodians.
Legal and compliance questions include who authorizes an agent’s payment, when software can bind its principal, what constitutes consent, who bears responsibility for erroneous purchases, and the need for auditable records for machine-driven transactions.
Summary based on 2 sources
Get a daily email with more Crypto stories
Sources
Live Bitcoin News • Sep 6, 2026
Treasury’s Stablecoin NPRM Regulates Issuers and Platforms Selling to U.S. Persons