Europe's Strategic Shift: Economic Constraints Threaten Security and Growth Amid Energy and Debt Challenges
October 25, 2026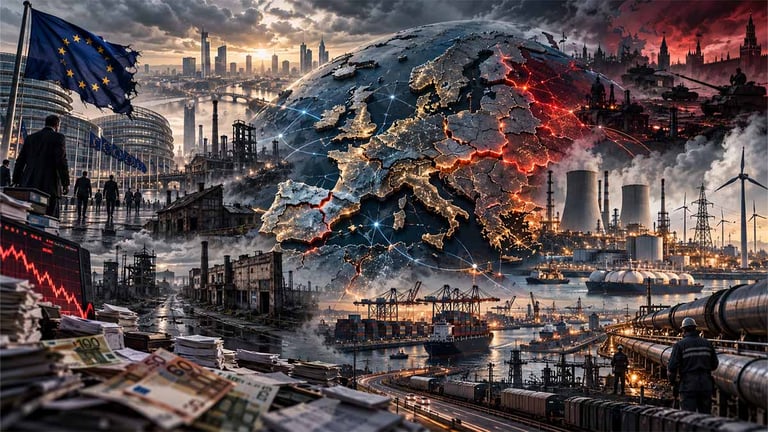

Europe faces a strategic shift as fiscal constraints, deindustrialisation, energy security concerns and political fragmentation converge, threatening its ability to finance security and growth over time.
The core problem is eroding economic flexibility; a continental, interconnected approach is needed to finance energy diversification, defence, and industrial renewal to avoid fragmentation and synchronized deficits.
As of October 2026, EU general government debt stands at about 82.9% of GDP, with Italy at 139.9%, France at 119.1%, Germany at 63.4%, and the UK debt near 94% of GDP in September 2026, highlighting varied debt profiles that shape investment capacity.
The next two years are pivotal as 2027 Russian gas restrictions test energy reliability and costs; France, Italy, and Germany face different debt- and investment-balancing challenges, while the UK, Poland and Romania confront parallel trade-offs, with the Commission’s forecasts shaping debt trajectories.
Defence-industrialization tensions collide with budgetary space and NATO’s 5% of GDP target for 2035, underscoring the need for procurement that actually builds sustainable domestic capabilities.
Medium-term risk lies in the cumulative impact of manageable decisions: potential delays in investment, loss of production capacity and weakened military readiness by 2028–2031.
Industrial trajectory shows euro-area industrial production down 1.1% year-on-year in August 2026 even as overall GDP edges higher, signaling divergence between services-led growth and weak manufacturing investment, with Italy and Germany showing sector-specific declines.
Energy independence does not automatically ensure competitiveness; reduced Russian gas imports leave exposure through LNG contracts and pipelines, with energy prices and reliability influencing where energy-intensive industries locate.
High debt burdens and deficits constrain financing for energy transition, defence, and industrial transformation, while ECB rate rises raise refinancing costs and potentially depress new investment.
Geopolitically, sanctions on Russia and Western responses in technology and finance are reshaping supply chains, making Europe more dependent on external suppliers and complicating strategic autonomy.
Summary based on 1 source
Get a daily email with more EU News stories
Source
https://debuglies.com • Oct 25, 2026
Europe’s Economic and Political Fragmentation: Debt – Deindustrialisation – Energy Sovereignty and the Geopolitical Redistribution of Power