Global AI Infrastructure Investment to Hit $31.6 Trillion by 2050, PwC Reports
September 2, 2026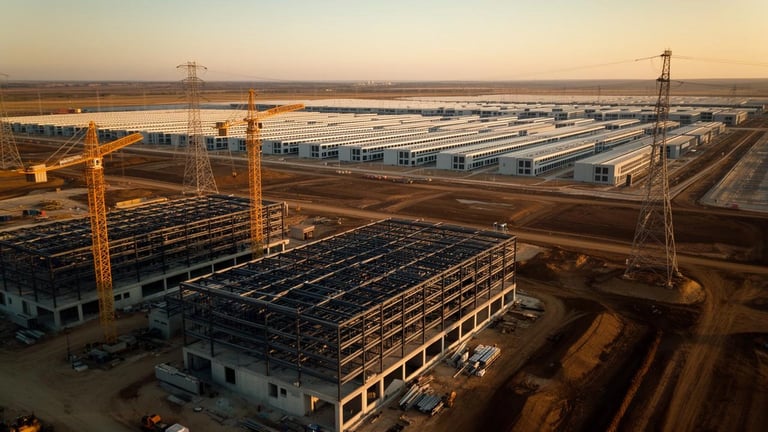


PwC projects global AI infrastructure investment will total about $31.6 trillion through 2050, with data center capex rising from roughly $800 billion in 2026 to $1.8 trillion by 2050, signaling a multidecade spending surge.
The United States is expected to account for around $15.1 trillion of this spending (about 48%), with Asia Pacific following at $8.2 trillion led by China and India, while Europe and the Middle East make up the remainder.
The investment mix is shifting toward ICT equipment, chips, servers, and networking gear, growing from 70% of spending today to about 93% by 2050 due to frequent hardware refresh cycles.
Beyond traditional liabilities, investors should scrutinize off-balance-sheet commitments to gauge true leverage and risk, as these could either secure scarce resources or unwind under adverse demand.
A practical bottleneck is infrastructure readiness—transformer lead times, grid connections, cooling, and approvals can slow deployment even where funding exists.
Regulatory and policy risks span local hurdles (electricity, environment, water, community concerns) and geopolitical tensions (US-China frictions, export controls), requiring assessment of temporary versus lasting impact.
Near-term operator implications include aligning underwriting to equipment-dominant capex and using financing and depreciation models that reflect chip-level economics, while prioritizing fibre access, permitting speed, and community consent alongside power.
S&P and Moody’s warn of hidden debts: if AI demand underperforms, fixed costs and excess capacity could threaten financial stability.
These insights sit within broader discussions on sovereign AI infrastructure and neocloud financing mechanisms shaping the industry landscape.
Institutional financing trends show growing shadow debt via SPVs, leases, and guarantees, with examples like Nvidia’s circular financing and SPV use by Oracle and Meta illustrating complexity.
A key caution is that not all AI ecosystem segments will sustain rapid growth and valuation expansion; investors must maintain discipline on valuations, earnings visibility, and execution.
Recent restrictions on New York data center construction are cited as indicative of potential future regulatory restraints, alongside regional opportunities and risks inherent in data center growth.
Summary based on 26 sources
Get a daily email with more World News stories
Sources
TNW | Artificial-intelligence • Sep 2, 2026
PwC projects that the global investment in AI infrastructure will reach $31.6 trillion by 2050
Breitbart • Sep 2, 2026
PwC Predicts $31 Trillion in Global AI Data Center Spending by 2050
The Edge Malaysia • Sep 2, 2026
Data centre spending to reach US$31.6 tril by 2050 on AI boom